

Most recent Economic Perspectives for Central and Eastern Europe
Czechia: growth holds steady as CNB tightens amid inflation risks
According to the preliminary estimate, the Czech GDP grew by 1.6% year-on-year in Q3, aligning closely with our full-year growth projection of 1.8%. Although we still have to wait for details, there is little doubt that the expansion remains driven by household spending. Household consumption has been supported by a resilient domestic labour market and a low unemployment rate (3.1% in September). The tight labour market continues to exert upward pressure on wages, creating an inflationary risk. Czech retail sales remain robust even as the latest business cycle surveys revealed that consumer confidence eased slightly to 104.3 points due to more cautious household financial outlooks.
The CNB raised its key two-week repo rate by 25 basis points to 4% in November. While the final CPI growth marginally slipped to 2.4% year-on-year in October (from 2.5% a month before), the central bank’s latest Macroeconomic Forecast indicates that the hike was mainly a proactive effort to anchor expectations. The CNB rate hike was broadly anticipated, as a significant surge in energy inflation is expected to come in the first months of 2027 (we project double-digit price growth for both gas and electricity). Food inflation is also set to rise, particularly for dairy products and meat. How high headline inflation will ultimately be depends primarily on the future evolution of natural gas prices. If gas prices increase further, average CPI inflation could climb as high as 4% next year, which would prompt the CNB to tighten its monetary policy screws further. For the time being though, in our baseline scenario, we expect annual average inflation to be 3.6% next year. As for the real GDP, we estimate growth will be slightly higher in 2027 than this year (+2.2% vs. +1.8%). We continue to view rate stability as the most likely scenario, especially if the still-stubborn core inflation gradually eases in line with our expectations.
Hungary: fiscal consolidation underpins euro ambitions
Hungary entered autumn with a mixed macroeconomic data set. GDP growth for the third quarter disappointed at 1.5% year-on-year. Growth was held back by agriculture due to the summer drought, while industry and household consumption provided support. A slight fourth-quarter improvement is expected, pushing annual growth to an estimated 1.7%. Our real growth forecast for 2027 stands slightly below the government's 2.4% target, at a more realistic 2.2%. External accounts remain a bright spot in the Hungarian economy, with the current account balance in surplus and a favourable net lending position.
Inflation remained low by historical standards at 2.0% year-on-year in October, though monthly prices rose by a non-negligible 0.4% largely due to motor fuel costs. Crucially, services inflation remained sticky at 5.2% year-on-year. Together with the upcoming 2027 wage agreements, this warrants caution. From a monetary policy perspective, the National Bank of Hungary (MNB) maintained its base rate at 5.5%. Despite headline inflation nearing the target, sticky services inflation and external uncertainties - especially high global energy prices - justify a wait-and-see approach. We do not expect another rate cut this year, though easing could resume in 2027 if conditions improve, potentially bringing the interest rate to 5.0% by year-end.
On the fiscal front, Prime Minister Magyar’s newly unveiled 2027 budget targets a significant consolidation, aiming to reduce the general government deficit from an estimated 7.5% in 2026 to 4.9% in 2027. Achieving this entails implementing robust fiscal measures, notably a HUF 1,500 billion spending cut alongside the phase-out of previous pre-election expenditures and the introduction of new corporate wealth taxes. Rather than dampening sentiment, this strong commitment to fiscal discipline was welcomed by international markets. Investors reacted positively to the credibility of the consolidation plan and the newly outlined roadmap for euro adoption. This bolstered confidence, drove down domestic government bond yields and strengthened the forint to four-week highs against the euro.
Bulgaria: risks are mounting, but growth remains solid
Security incidents in the western Black Sea continued in late October, leading to industry reports indicating higher war-risk insurance costs and freight rates. Although there is currently little evidence of a material decline in activity at Bulgaria's main ports, the development represents an upside risk to inflation through higher transport, insurance and import costs.
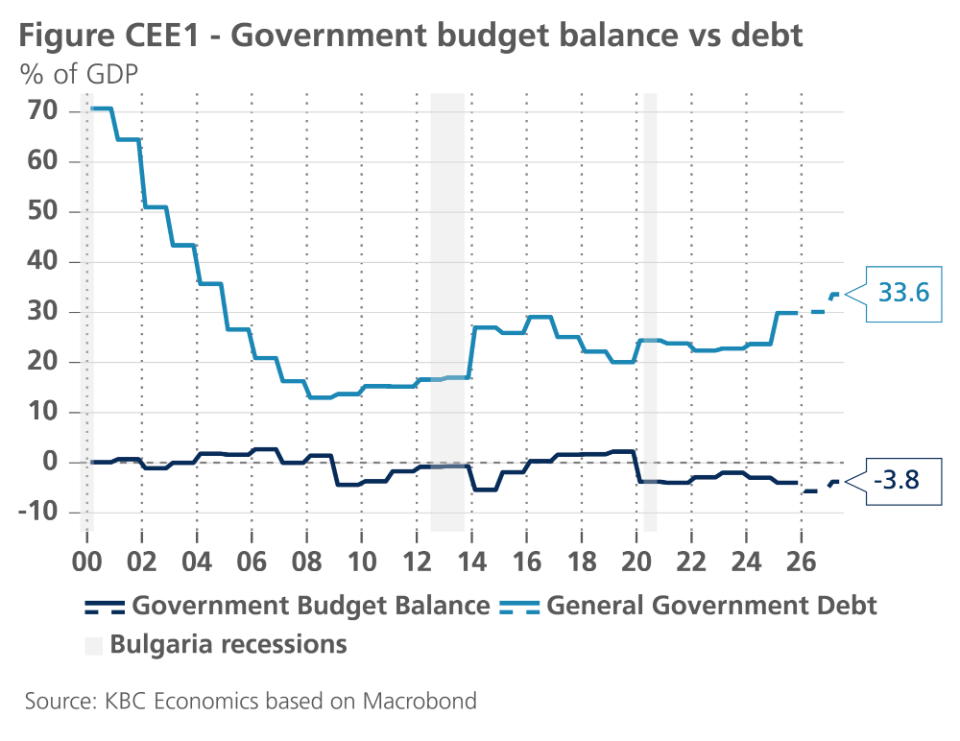
The government unveiled the full 2027 state budget on 5 November, initiating parliamentary scrutiny ahead of an expected vote in December. The budget confirms the authorities' preference for gradual rather than aggressive fiscal consolidation. Fiscal policy is thus likely to remain broadly supportive for growth in 2027, while leaving questions about the speed and credibility of the deficit reduction under the excessive deficit procedure. We expect government debt to increase from 30.1% of GDP to 33.6 in 2027, with a government budget balance to improve from -5.7% of GDP to -3.8% (see figure CEE1).
Bulgarian HICP inflation rose to 5.9% in October, from 5.7% a month earlier, reflecting strong price increases in ‘Clothing and footwear’, ‘Recreation, sport and culture’, and ‘Education services’. The latest data leave our inflation forecasts unchanged, with average inflation expected at 5.0% in 2026 and 3.8% in 2027. Economic growth continues at a steady pace, with the Q3 flash estimate indicating quarterly GDP growth of 0.6%. We therefore maintain our GDP growth forecasts of 2.6% for 2026 and 2.4% for 2027.
Slovakia: confidence recovers as fiscal risks mount
Last month, despite coalition infighting, Robert Fico ultimately secured parliamentary approval for the 2027 budget. However, the final budget largely abandoned plans for further fiscal consolidation, leaving Slovakia's public finances on a persistently weak trajectory. We forecast the general government deficit to remain elevated at around 5.5% of GDP in 2027, while public debt is projected to rise to approximately 65% of GDP.
Government support measures left a visible imprint on the inflation data. A reduction in fares for public rail and bus transport contributed to lower transport costs, helping to offset increases in fuel prices. Harmonised inflation (HICP) slowed to 2.9% year-on-year in October, the lowest reading in almost two years. At the same time, food prices recorded their first increase in several months, suggesting that the period of food price deflation may be ending, although the annual food inflation figure will remain negative. We estimate average HICP inflation at 3.8% in 2026, easing only modestly to 3.6% in 2027.
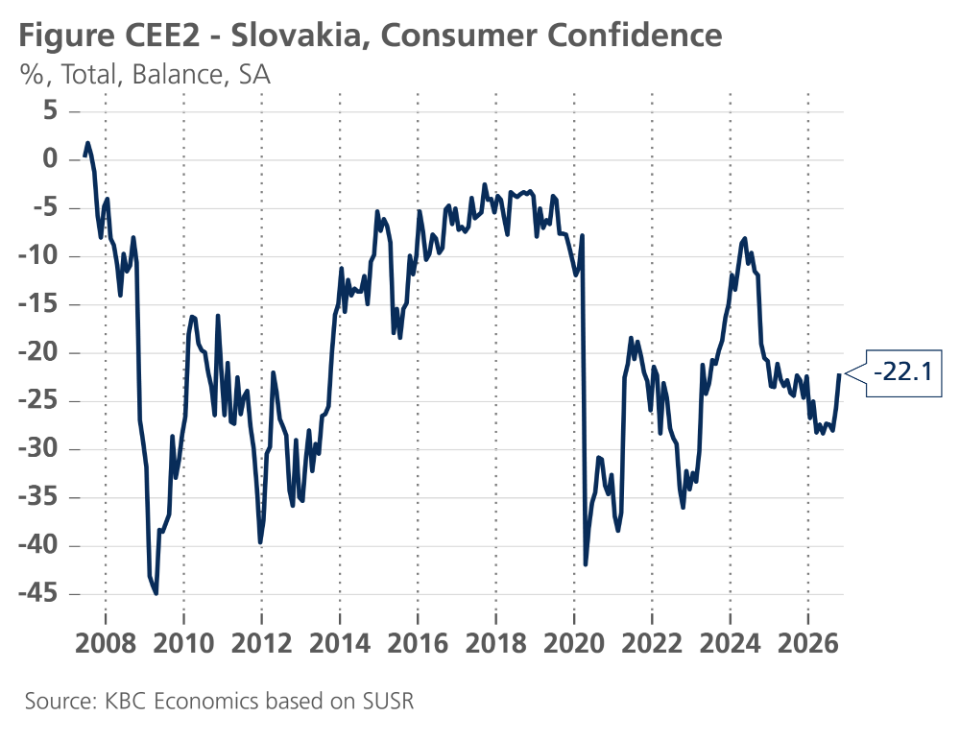
The Slovak economy entered the final quarter of 2026 with improving confidence indicators and easing inflation concerns. Business and consumer surveys showed a notable strengthening in sentiment during October. The consumer confidence indicator rose to -22.1 (see figure CEE2), its highest level since March 2025, while the broader Economic Sentiment Indicator improved by 6.6 points. The strengthening was broad-based across services, industry and construction, while consumer confidence also recovered strongly following weaker readings in late summer. The improvement in sentiment comes after a weak third quarter, when GDP expanded by only 0.06% quarter-on-quarter. According to the flash estimate, household consumption and investment were the main drivers keeping economic growth in positive territory. We estimate average GDP growth of 0.7% in 2026. The European Commission's Autumn 2026 forecast similarly expects growth to remain subdued at 0.8%, reflecting the drag from fiscal consolidation, elevated energy costs and weak external demand. We forecast growth to recover modestly to 1.2% in 2027. Nevertheless, persistent energy-price pressures and Slovakia's strong dependence on European manufacturing demand, particularly from Germany, remain important downside risks to the outlook.
Poland: a rate hike remains in sight
Poland's economic growth lost some momentum in Q3, with GDP expanding by 3.5% year-on-year down from 4.1% in Q2 and marginally below expectations. Nevertheless, the economy continued to grow at a solid 0.8% quarter-on-quarter and remains one of the fastest-growing economies in the region, supported by resilient household demand, a tight labour market and inflows of EU funds. We expect GDP growth to average 3.6% in 2026 before moderating slightly to 3.0% in 2027.
The NBP left its policy rate unchanged at 3.75%, in line with expectations. October inflation slowed from 4.1% to 3.5% year-on-year, largely due to a government programme aimed at reducing fuel prices, bringing headline inflation back to the upper limit of the central bank's tolerance band. Despite the recent easing in price pressures, the latest NBP projections point to persistent inflationary risks, with inflation expected to remain within a 3.1-5.3% range in 2027 under an unchanged interest-rate path, underscoring the limited room for a more accommodative monetary policy stance.
These concerns were echoed by Governor Adam Glapiński during the November press conference. While indicating that a December rate hike remains unlikely, he acknowledged that inflation risks have increased since the previous meeting and suggested that the key policy debate is shifting towards early 2027. This broadly aligns with our baseline scenario, which envisages at least one 25bp rate hike in the first quarter of next year. We expect harmonised inflation to average 3.2% in 2026 and accelerate to 3.5% in 2027.
For the zloty, however, the conference provided little support. Glapiński reiterated that the weakening of the Polish currency is not a concern for the NBP and that the central bank has no view on the "appropriate" level of the exchange rate. Combined with only a gradual prospect of further domestic tightening and a narrowing interest-rate differential vis-à-vis the ECB and potentially the Fed, the zloty remains vulnerable. We expect EUR/PLN to reach 4.43 by the end of this year before weakening further to 4.50 by the end of Q3 2027.