

Most recent Economic Perspectives for Central and Eastern Europe
Hungary: MNB tightens inflation ambitions
The Hungarian central bank (MNB) has lowered its inflation target from 3.0% to 2.5%, effective from 2028, while retaining the ±1 percentage point tolerance band. The delayed implementation gives households and firms time to adjust their inflation expectations. The move is closely linked to Hungary's ambition to meet the Maastricht criteria and move closer to euro adoption by around 2030. By bringing its inflation objective closer to the European Central Bank (ECB)'s 2% target (see figure CEE1), the MNB is signalling a stronger commitment to price stability and a more stable exchange rate. In addition, the MNB has announced that it will align its monetary policy meeting schedule more closely with that of the ECB from 2027.
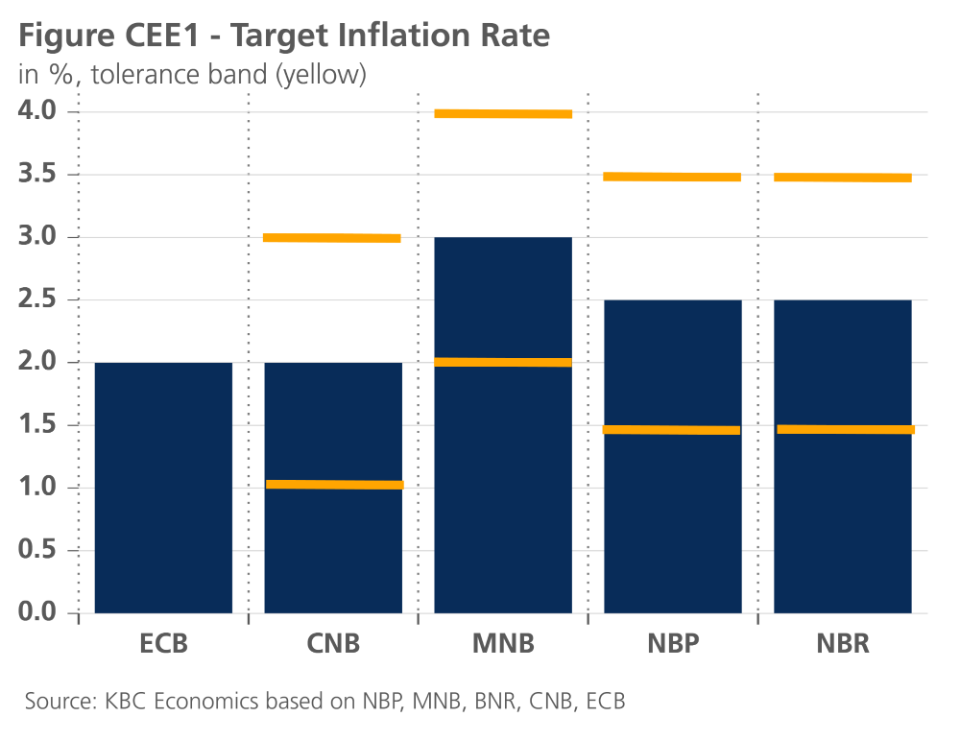
The MNB acknowledges that achieving lower inflation may temporarily weigh on economic growth, as it could require tighter monetary policy and higher real interest rates. The success of the new target will depend on whether businesses and households incorporate it into wage negotiations, pricing decisions and long-term planning. The decision also reinforces expectations that the central bank will maintain a cautious policy stance. As expected, the MNB kept the base rate unchanged at 5.5% at its October meeting. Looking ahead, we expect the policy rate to remain at this level through end-2026, with a new easing cycle likely to begin only once it becomes clearer that the 2.5% inflation target can be achieved. Under this scenario, the policy rate could decline towards 4.5% by end-2027.
Hungarian CPI inflation came in at 1.56% year-on-year, below both market expectations and our forecast. The downside surprise was mainly driven by food prices, which recorded zero month-on-month growth despite rising producer prices, higher price expectations and increasing farm-gate prices. Motor fuel prices rose by 1.71% month-on-month, also below our expectation. Meanwhile, services inflation developed broadly in line with expectations, thus returning to more normal dynamics after the stronger summer readings. Although price expectations in the services sector increased in September, they remain at relatively low levels. On the goods side, we do not expect the weak to negative price growth observed in durables and clothing during the summer to persist, given rising producer prices, higher price expectations and the depreciation of the forint from its June lows. We continue to expect average HICP headline of 2.2% in 2026, rising to 3.3% in 2027, unchanged from our previous forecast.
On the fiscal side, the IMF recently warned that Hungary's budget deficit is likely to remain elevated at 7-7.5% of GDP in 2026, broadly in line with our forecast. We expect the deficit to narrow to 5.0% of GDP in 2027, close to the 4.9% target referenced by the Prime Minister this week. As for economic activity, we maintain our 2026 GDP growth forecast at 1.8%, while projecting growth of 2.4% in 2027.
Czechia: inflation rebounds while the CNB maintains a hawkish pause
In Czechia, price pressures also showed signs of renewed momentum, disrupting the disinflationary narrative. The annual inflation rate accelerated to a five-month high of 2.5% in September 2026, up from 1.9% in August. The increase was mainly driven by higher transportation costs and a moderation in the pace of food price deflation. Despite this uptick, inflation remains within the upper half of the CNB's tolerance band. The CNB Board voted unanimously to keep the two-week repo rate unchanged at 3.75% at its late September meeting, extending its pause. Policymakers maintained a cautiously hawkish tone, emphasising upside risks stemming from commodity markets, global yields, and persistent services inflation. The central bank continues to signal that rates will remain higher for longer, and many market participants (including us) are pricing in a potential 25 basis points rate hike in November.
Meanwhile, economic activity is gradually recovering. Domestic demand and household consumption are supported by solid real income growth, although the pace of industrial recovery remains constrained by the continued weakness in the German manufacturing sector. The Czech fiscal trajectory remains relatively stable compared to regional peers, though the budget is still in deficit. We expect the budget balance to land at approximately -2.8% of GDP in 2026, widening to -3.6% in 2027. Gross public debt remains contained, projected to reach around 45.8% in 2026 and 47.6% in 2027, leaving Czechia with one of the healthiest fiscal positions in the region.
The Czech Koruna experienced a period of moderate volatility in recent weeks. The currency's trajectory was influenced less by domestic political developments and more by external macroeconomic factors, particularly the stagnation in the German industrial sector and broader shifts in global risk sentiment driven by geopolitical tensions. This external pressure, coupled with the CNB's hawkish pause, has kept the Koruna relatively range-bound against the Euro.
Slovakia: 2027 budget approved without new consolidation measures
The 2027 budget approved on 14 October sets a general government deficit target of 4.94% of GDP, wider than the 4.37% the government expects for this year. It is the first budget of Fico’s current term without a new fiscal consolidation package, marking a break from earlier efforts to bring the deficit towards the EU’s 3% reference value. The government aims to narrow the deficit to 4.5% and then 4% of GDP over the following two years, but has yet to specify the additional measures needed to achieve these targets. The Council for Budget Responsibility has criticised the looser fiscal stance despite expectations of stronger economic growth, warning that public debt could reach 70% of GDP in 2028 without renewed consolidation. With our GDP growth forecast at just 0.7% this year and a modest pickup to 1.2% in 2027, revenue growth is likely to remain subdued, while the election calendar leaves little room for spending restraint. We therefore expect the deficit to reach 5.0% of GDP this year and widen to 5.5% in 2027.
HICP inflation eased to 3.0% year-on-year in September, its lowest level since September 2024. The slowdown was driven by continued deflation in food and non-alcoholic beverages, with prices falling by 3.2% year-on-year, despite rising energy prices. Services inflation also continued to moderate, reaching 3.9% year-on-year in September. We maintain our forecast for average HICP inflation at 4.1% in 2026, followed by a decline to 3.6% in 2027.
Bulgaria: Black Sea tensions have limited economic impact for now
A day after an attack on a cargo vessel off the Romanian coast, two merchant ships were reportedly struck off the Bulgarian coast. Although the direct macroeconomic impact of this event on Bulgaria remains limited for now, prolonged tensions in the Black Sea could lead to higher war-risk insurance premiums, increased transport costs and the rerouting of maritime trade, weighing on the competitiveness of Black Sea ports. Tourism could also be impacted as persistent security concerns could deter visitors. For now, we expect the economy to remain resilient with growth averaging 2.6% in 2026 and 2.4% in 2027.
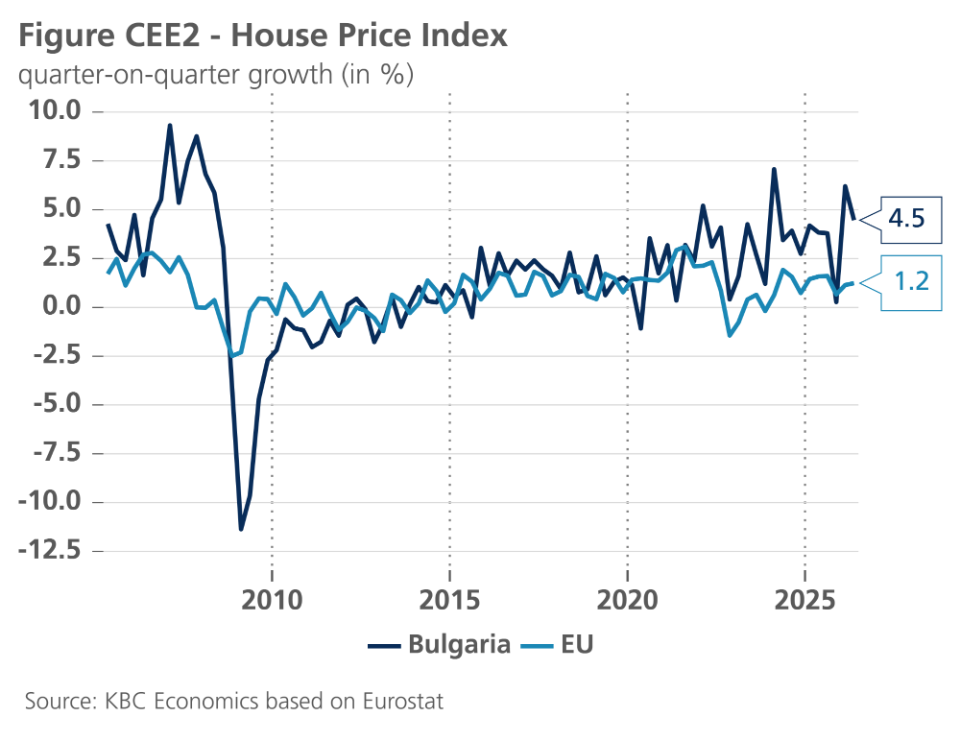
Bulgarian house price growth also continues to exceed expectations following euro adoption. After rising by 6.2% quarter-on-quarter in Q1, house prices increased by a further 4.5% in Q2 2026 (see figure CEE2). We therefore revise our 2026 average annual nominal house price growth forecast upward to 11%, while projecting growth of 6.5% in 2027.
Bulgarian HICP inflation accelerated from 5.1% in August to 5.6% in September. In month-on-month terms, prices declined by 0.1%, although this largely reflected seasonal factors, particularly lower prices for tourism-related services following the summer season. Services inflation remains a key concern, rising to 7.6% in September from 7.2% year-on-year in August. Against this backdrop, we expect average HICP inflation to reach 5.0% in 2026, before moderating to 3.8% in 2027.
Romania: the leu remains a barometer of political risk
The prospect of a functioning government has recently provided some support to Romanian assets. Government borrowing costs have declined, the Bucharest stock exchange has advanced, and the leu has strengthened modestly, although EUR/RON remains above 5.30, well above pre-crisis levels, suggesting that investors continue to demand a political and fiscal risk premium. While the risk of snap elections has receded, questions remain about the durability of the new arrangement. The government will depend on parliamentary support from parties that have chosen not to participate directly in the cabinet, while difficult fiscal consolidation measures still need to be implemented against a backdrop of weak economic growth, for which we expect -0.5% in 2026, 2.2% in 2027. We therefore continue to expect a gradual weakening of the leu to around 5.33 by the fourth quarter of 2026 and 5.37 by the fourth quarter of 2027. Importantly, despite the political turmoil, S&P Global Ratings maintained Romania's sovereign rating at BBB-/A-3 with a negative outlook, preserving the country's investment-grade status.
After months of declining inflation, largely driven by favourable base effects, recent increases in energy prices pushed headline HICP inflation up to 6.5% year-on-year in September, from 6.3% in August. We expect average annual inflation to reach 8.2% in 2026, before moderating to 4.3% in 2027. The National Bank of Romania (NBR) kept its key policy rate unchanged at 6.50% at its October meeting. While the central bank acknowledged that the disinflationary trend has broadly continued, it highlighted significant upside risks to inflation stemming from geopolitical tensions in the Middle East, elevated energy prices, exchange-rate pressures and robust wage growth. Against this backdrop, we expect the NBR to deliver one additional rate hike by year-end, bringing the policy rate to 6.75%, where we expect it to remain throughout 2027.
Poland: standoff, downgrade and a stubborn deficit
Poland is facing important fiscal challenges. In September, Moody's downgraded Poland's sovereign rating from A2 to A3. The agency cited persistently large fiscal deficits, rising government debt and debt-servicing costs, and weakened fiscal policy effectiveness. Political constraints, including tensions between the government and president and the approaching 2027 parliamentary election, further complicate fiscal consolidation. The downgrade brings Moody's rating broadly into line with Fitch and S&P, which both rate Poland A-.
The draft 2027 budget offers little indication of near-term fiscal adjustment. The general government deficit is projected at 7.1% of GDP, unchanged from 2026 and substantially above the government's earlier consolidation trajectory. The central government budget deficit is set at a record PLN 281.2 billion, with defence spending projected at 4.5% of GDP and debt-servicing costs reaching PLN 107 billion.
Inflation has accelerated again, driven largely by higher energy and fuel prices. Year-on-year CPI inflation rose from 3.4% to 4.1% in September, its highest level since June 2025, while transport prices increased by 17.9% year-on-year. To ease the pressure, the government reduced VAT on fuel from 23% to 8%, lowered excise duties and reintroduced maximum retail fuel prices through the end of 2026. These measures should have an almost immediate disinflationary impact, with the fuel tax cuts alone likely to lower headline inflation by more than 0.5 percentage points. Against this backdrop, we have revised our inflation outlook, now expecting average annual HICP inflation of 3.2% in 2026, slightly below our previous forecast, before accelerating to 3.7% in 2027, up from our earlier projection of 3.0%.
The National Bank of Poland kept its reference rate unchanged at 3.75% in October, its sixth consecutive hold, amid continued uncertainty surrounding the Middle East conflict and persistent inflationary pressures. However, influential NBP Governor Adam Glapiński has indicated that he does not expect an interest rate increase at the November meeting. According to him, the Monetary Policy Council has not yet seen evidence that higher oil and gas prices are feeding through into broader price developments, arguing that the recent increase in inflation to around 4% mainly reflects higher fuel prices. In his view, the key issue will be the NBP's November inflation projection and whether it points to meaningful second-round effects from higher energy prices.
In our view, a rate increase in November is therefore less likely. Nevertheless, the upward revision to our inflation outlook suggests that the next policy move should be a hike. The key question is the timing and scale of the tightening. We now expect the NBP to raise its reference rate by 25 basis points to 4.00% either in December 2026 or in the first quarter of next year. The NBP could then maintain the policy rate at that level throughout 2027.