
Economic Perspectives for Belgium
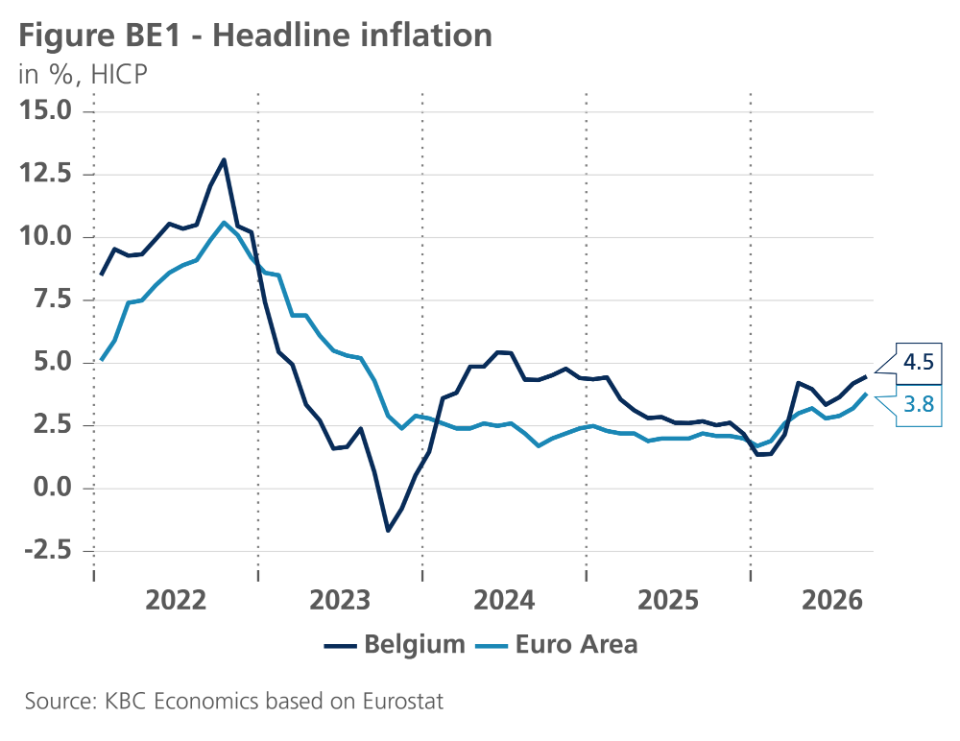
Belgian inflation (based on the HICP) reached a fresh peak in September, with the rate rising 0.3 percentage points to 4.5%. The rise was a bit lower-than-expected and slower than the 0.6 percentage points increase in euro area inflation last month. At 4.5%, Belgian headline inflation still is well above the euro area figure (3.8%), though (see figure BE1). As in the previous month, the increase was entirely driven by higher energy inflation (from 21.9% to 30.6%). Core inflation (which excludes energy and food) fell from 3.1% to 2.6%, with both non-energy goods inflation and services inflation down. The decline indicates that the energy shock is not further broadening out to other parts of the inflation basket. Meanwhile, the futures curve for crude oil and gas prices moved higher compared to a month ago. As a result, we upwardly revised the outlook for 2027 average inflation, from 2.4% to 2.6%. The inflation outlook for 2026 was left unchanged at 3.7%, with the lower-than-expected September reading compensating for the slightly upwardly revised inflation forecast for the three final months of the year.
Mixed signals from September’s confidence figures
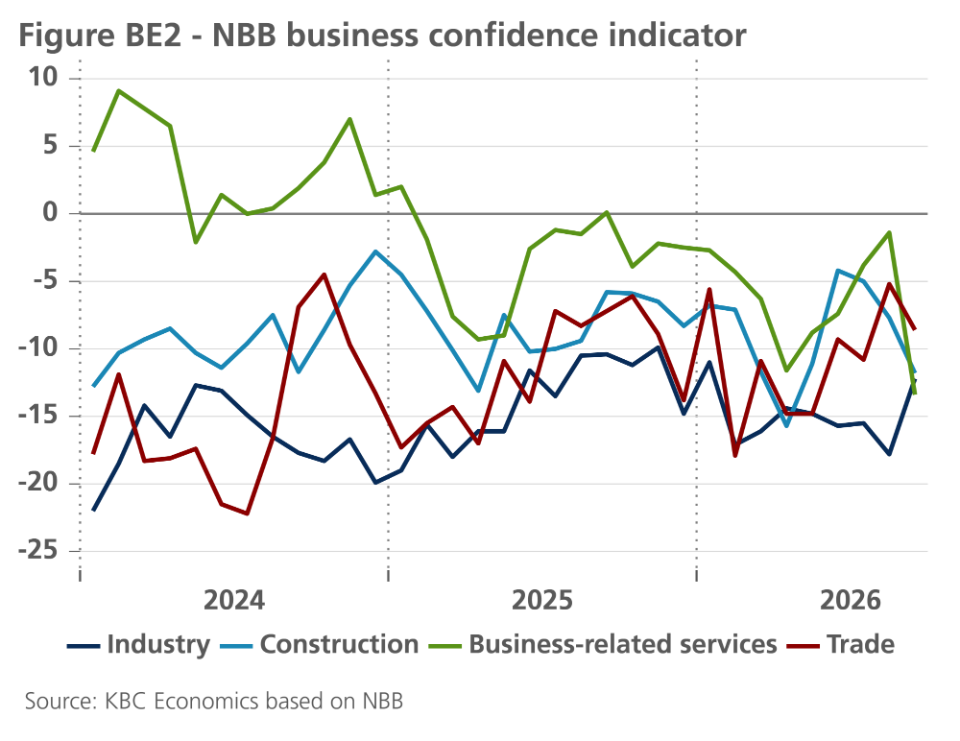
The ongoing inflationary pressures will negatively impact households’ real purchasing power, as the indexation mechanism will reflect the higher inflation with a time lag and only partially, given that petrol and diesel prices are excluded from the health index. Moreover, consumers’ expectations regarding the economic situation in Belgium have become more pessimistic, which was the main reason for the further weakening of the NBB’s consumer confidence indicator in September and October. Looking ahead, the pessimism combined with the loss in purchasing power will likely weaken private consumption growth. Contrary to this, a slight increase in the NBB’s business barometer in September has offset the dip in the indicator in August. Remarkably, sentiment strengthened in industry but declined in the other sectors (see figure BE2). In line with this, the worsening of business leaders’ assessment of export-order books over the summer has fully been reversed in September. The latter suggests that exports still perform well, as they did in the first half of 2026. The risk exists that the energy shock triggers a renewed loss of Belgium’s wage cost competitiveness, though, limiting export dynamics in the quarters ahead.
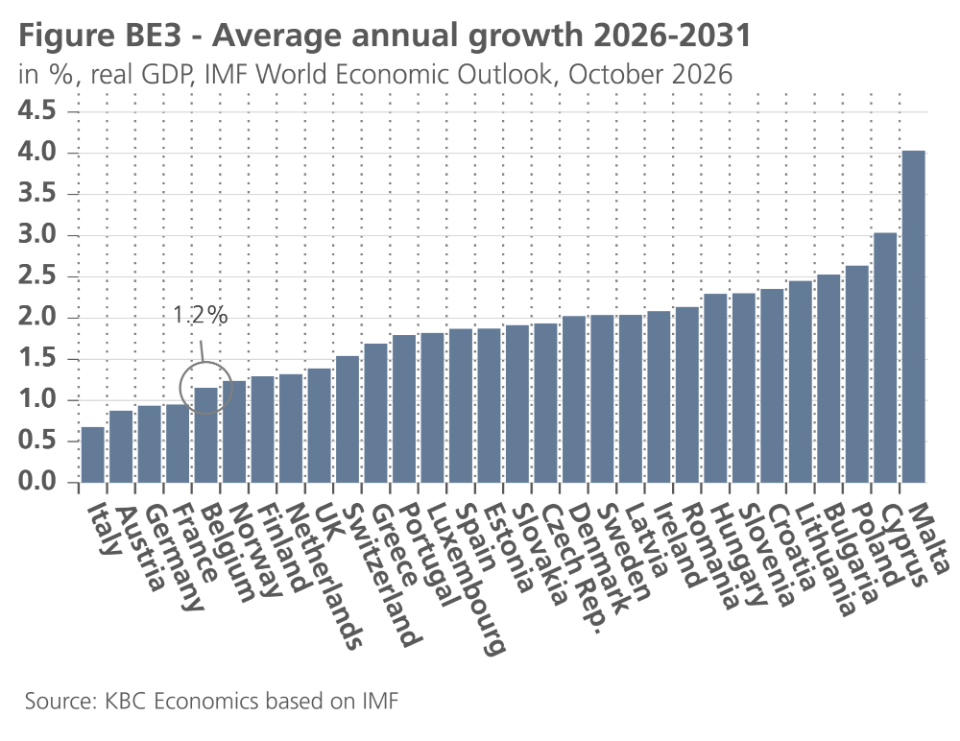
On balance, we lowered the path of Belgian qoq growth in 2027, resulting in a slight downward adjustment of the outlook for real GDP growth in 2027 as a whole, to 0.8% from 0.9% previously. Note that the National Accounts Institute (NAI) has recently revised past Belgian real growth rates downwards, from 1.1% to 0.9% in 2024 and from 1.0% to 0.9% in 2025. This resulted in a somewhat higher growth overhang from 2025 into 2026 (i.e. 0.28 instead of 0.22 percentage points). Also, the revised quarterly GDP path implies slightly higher qoq growth in Q2 2026 (i.e., 0.14% instead of 0.03%). As a result, we revised 2026 annual growth upwards, from 0.6% to 0.7%. Supposing our 2026-2027 outlook comes true, this would mean that the Belgian economy will have grown by a below 1% rate for four years in a row. KBC’s updated growth forecast for 2027 (0.8%) is more downbeat than the projection recently published by the IMF in its October World Economic Outlook (1.1%). Interestingly, the IMF's outlook extends to 2031. At 1.2%, the average annual real GDP growth in 2026-2031 projected by the IMF for Belgium is among the lowest in Europe (albeit slightly higher than in the three large countries of Germany, France and Italy, see figure BE3).
Besides GDP growth, the NAI also adjusted past data for several other macro data, including public finances. E.g., the public debt-to-GDP ratio was revised slightly upwards from 107.9% to 108.1% of GDP, but the general government deficit for 2025 was unchanged at 5.2% of GDP. The biggest revision was made for the current account deficit in 2025, which was adjusted sharply downwards to 0.2% of GDP, from 1.9% previously. This adjustment is mainly due to improved measurements of household spending across the border and online. In line with the NAI revisions, and following our updates for inflation and real GDP growth in 2027 (see above), we also updated the outlook for the current account balance and public finances, with only minor changes made for the latter (see table). We also changed the outlook for 2026 end-of-year unemployment. Surprisingly, Belgium’s harmonised unemployment rate fell to 5.9% in August, from 6.3% in June. The series, which is based on Eurostat’s Labour Force Survey, has been relatively volatile over the past year, with the observed decline likely impacted by Belgium’s unemployment benefits reform. The lower August figure made us update the outlook to 6.2% at the end of 2026.
Weaker house price growth
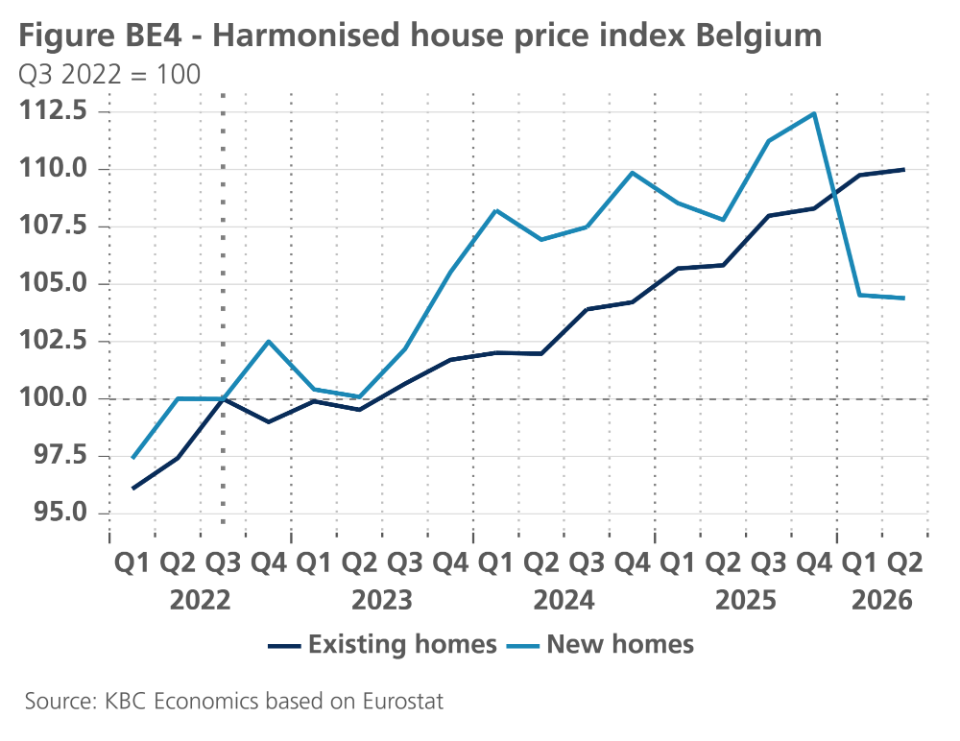
After the 0.9% decline in Q1 2026, Belgian house prices (based on Eurostat’s harmonised definition) rose again in Q2 2026 compared to the previous quarter, albeit slightly by 0.1% (see also KBC’s Economic Brief “House prices in the EU continued to rise in Q2 2026, but country divergences persist”). Compared to the same quarter a year earlier, the price increase in Q2 was 2.1%. This figure implies a slight acceleration in the yoy dynamic compared to Q1 (1.9%), but remains well below the average annual increase in the four quarters of 2025 (3.2%). As in Q1, the house price figure concealed a divergence between new and existing homes (see figure BE4). The price of new homes continued to fall in Q2 (-0.1%), but much less than in Q1 (-7.0%). That of existing homes rose in Q2 (0.2%), but also much less than in Q1 (1.3%). As a result of the somewhat weaker than expected Q2 figure and the recent rise in long-term interest rates, we adjusted the price outlook downwards. We now see an annual house price increase of 1.5% in 2026 (coming from 2.1% in our earlier forecast) and 2.8% in 2027 (coming from 3.0%). With headline inflation expected at 3.7%, this price forecast for 2026 implies a real house price decline (i.e. adjusted for HICP inflation) of more than 2%.