
House prices in the EU continued to rise in Q2 2026, but country divergences persist
Click here to open PDF
According to new Eurostat figures, prices on the European housing market continued to rise in the second quarter of 2026. The quarterly rate of price growth strengthened slightly, from 1.1% to 1.2%. However, the year-on-year growth momentum slowed down further and fell below 5%. There were again significant differences between member states. In two countries (coming from three in Q1), prices fell compared to the previous quarter, albeit slightly: France and Hungary. In eight countries (the same number as in Q1), the price increase was more than 3%: Lithuania, Bulgaria, Romania, Latvia, Portugal, Estonia, Spain and Austria. In Belgium, prices rose again, albeit slightly (+0.1%), after the correction (-0.9%) in the first quarter. The general price trend in Belgium again concealed a split development, but less than in Q1, with prices of existing homes rising further (+0.2%) and those of new ones falling further (-0.1%).
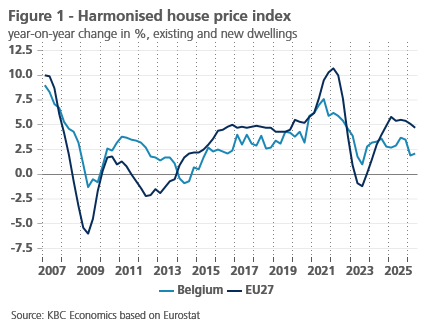
Eurostat recently published house price figures for the second quarter of 2026. It is the harmonised house price index for the EU member states, which takes into account both existing and new homes and corrects for price changes resulting from changes in the characteristics of the property sold. In the EU as a whole, house prices rose by 1.2% in Q2 2026 compared to the previous quarter. This is a slightly higher figure than in Q1 2026 (1.1%), when quarterly price dynamics had already strengthened compared to Q4 2025 (0.7%). Compared to the same quarter a year earlier, house prices in the EU were 4.7% higher in Q2 2026, which is a further slowdown in the year-on-year growth dynamics compared to those in the previous quarters (see figure 1).
Large country differences
In Q2 2026, there were only two countries, France and Hungary, where house prices fell compared to the previous quarter (see figure 2). This is less than in the previous quarters. Moreover, the price decline in both countries was limited to 0.8% and 1.4% respectively. In France, the correction was a continuation of a price decline in the two previous quarters. The housing market continues to suffer from weakness in the country, with house prices in Q2 2026 still 6.6% below the peak of Q3 2022. In Finland, Luxembourg, Germany and Sweden, which also had to deal with a sharp correction earlier, the price level in Q2 2026 was also still below the peak of 2022 (by 14.1%, 13.5%, 8.3% and 2.5% respectively), but the market there is now recovering with positive quarter-on-quarter growth figures in Q2 2026 as well (0.3%, 1.1%, 0.3% and 1.9% respectively).
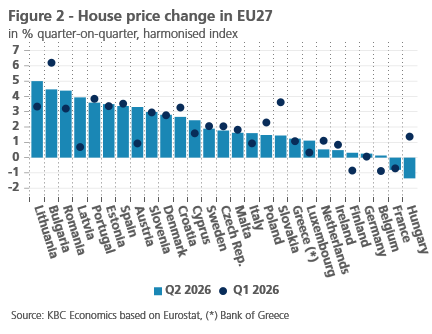
The Q2 price decline in Hungary stands out and follows an already considerable weakening of the quarterly price dynamics in the two previous quarters. Apart from the negative Q2 2026 figure, Hungary has only experienced one other negative quarterly figure in recent years (Q4 2022), which was followed by consecutive strong quarterly figures. In Q2 2026, house prices in Hungary were still no less than 53% higher than the average in 2022. The country thus experienced one of the strongest house price increases in the EU in recent years, but that now seems to be coming to an end.
In eight EU countries, quarterly house price growth in Q2 2026 was more than 3%. That is the same number as in Q1 2026 and twice as many as in Q4 2025. Six of these countries were the same as in Q1 2026, namely Lithuania (5.0%), Bulgaria (4.5%), Romania (4.4%), Portugal (3.6%), Estonia (3.5%) and Spain (3.4%). In Latvia (3.9%) and Austria (3.3%), price dynamics accelerated to above 3%. With the exception of Estonia, Latvia and Austria, these are countries where price dynamics have also been particularly strong in (most) previous quarters and where there has been little or no cooling of the housing market in the past.
Compared to the same quarter a year earlier, three EU countries showed a decline in house prices in the second quarter of 2026: Finland (-2.7%), Luxembourg (-2.2%) and France (-0.8%). The highest annual price increase was again recorded in Portugal (+16.5%). Eight other Eastern and Southern European countries also recorded double-digit annual price increases in Q2 2026: Bulgaria (+15.5%), Lithuania (+14.3%), Slovakia (+13.6%), Croatia (+12.7%), Spain (12.1%), Romania (12.1%), Latvia (11.4%) and Hungary (10.2%). Romania stands out in particular, where the year-on-year increase accelerated from 7.8% in Q1 to 12.1% in Q2 2026 due to the pick-up in the quarterly increase.
Existing versus new homes
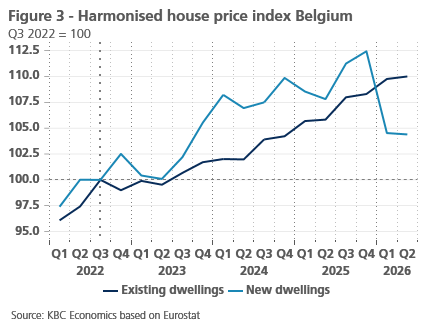
After the 0.9% decline in Q1 2026, Belgian house prices rose again in Q2 2026 compared to the previous quarter, albeit slightly by 0.1% (see figure 2). Compared to the same quarter a year earlier, the price increase in Q2 was 2.1%. This figure implies a slight acceleration in the year-on-year growth dynamics compared to Q1 (1.9%), but remains well below the average annual increase in the four quarters of 2025 (3.2%) (see figure 1). As in the first quarter, the general house price figure concealed a different dynamic between new and existing homes (see figure 3). The price of new homes continued to fall in Q2 compared to the previous quarter (-0.1%), but much less than in Q1 (-7.0%). That of existing homes rose in Q2 (0.2%), but also much less than in Q1 (1.3%).
In contrast to the Belgian situation, there was no difference in the quarterly rate of increase of new and existing homes in the EU as a whole in Q2 2026 (both +1.2%). However, in addition to Belgium, there are many other EU countries where the price dynamics for the two segments differed greatly in Q2. In Slovenia, the Netherlands and the Czech Republic, prices for new homes also fell in Q2 but rose for existing ones. Conversely, there are countries (Italy and Luxembourg, in particular) where the prices of new homes rose more sharply than those of existing ones.
As expected, the negative Belgian Q1 figure was not a harbinger of a further price correction in Q2, although the Q2 figure also remained rather weak. The fundamentals of the Belgian housing market are not very bad and, moreover, at least according to the KBC valuation model, the market is no longer overvalued (the model points to a very slight overvaluation of 0.4% in Q2 2026). Nevertheless, as a result of the somewhat weaker than expected Q2 figure and the continued rise in long-term interest rates, we are adjusting our outlook for the house price development in Belgium in 2026 slightly downwards. For the whole of (existing and new) homes, we now assume an annual price increase of 1.5% in 2026 (coming from 2.1% in our earlier forecast). With headline inflation expected at 3.7%, this house price forecast for 2026 does imply a real house price decline (i.e. adjusted for HICP inflation) of more than 2%.